What neobank would you recommend for a UK startup?
- Models
- 12
- Answers
- 114
- Brands named
- 18
What neobank would you recommend for a UK startup?
12 AI models · 114 answers · ranked by score
ordered by brand score: 100 pts for rank 1 → 20 for rank 5 · no mention = 0
- #1Starling Bank87brand score77first choice12345
- #2Revolut69brand score48first choice
- #3Tide60brand score41first choice
- #4Monzo49brand score31first choice
- #5Wise24brand score21first choice
Show 13 moreShow less
- #6Anna Money4brand score4first choice
- #7Mettle2brand score2first choice
- #8N261brand score1first choice
- #9Qonto1brand score1first choice
- #10Mercury1brand score0first choice
- #11Cashplus1brand score1first choice
- #12Chime0brand score0first choice
- #13Zempler Bank0brand score0first choice
- #14Airwallex0brand score0first choice
- #15Bunq0brand score0first choice
- #16Iwoca0brand score0first choice
- #17Petal0brand score0first choice
- #18Virgin Money0brand score0first choice
Each bar covers the middle half of one model’s answers (Q1–Q3); the line inside it is that model’s median rank for the times it recommended the brand. The badge under a brand says how far apart the models are on it, and “first choice” scores rank 1 far above the rest — a brand can place well overall and still rarely lead an answer.
Swipe left for the full report
Brand by model
Median rank each model gave each brand.
Scroll the table sideways to see every model →
| deepseek-v4.1-flash | gpt-6-astra | gemini-3.8-flash | gemini-3.7-flash | grok-4.6 | qwen3.8-max | claude-opus-5 | gemini-3.5-flash-lite | kimi-k3 | gpt-5.6-luna | mistral-medium-3.5 | claude-haiku-4.5 | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Starling Bank | 1.0 | 1.0 | 1.0 | 1.0 | 1.0 | 1.0 | 2.0 | 3.5 | 1.5 | 1.0 | 2.0 | 4.0 |
| Revolut | 3.0 | 3.0 | 3.0 | 2.5 | 3.0 | 3.0 | 3.0 | 1.0 | 3.0 | 3.0 | 1.0 | 2.0 |
| Tide | 4.0 | 4.0 | 3.0 | 3.5 | 2.0 | 4.0 | 1.0 | 4.0 | 2.0 | 2.0 | 3.0 | 3.0 |
| Monzo | 2.0 | 2.0 | 2.0 | 3.5 | 4.0 | 2.0 | 4.0 | 4.0 | 4.0 | 4.0 | 4.0 | — |
| Wise | 5.0 | 5.0 | 5.0 | 5.0 | 5.0 | — | 5.0 | 2.0 | 5.0 | 5.0 | — | 1.0 |
| Anna Money | 5.0 | — | — | — | 5.0 | 5.0 | — | — | 5.0 | 5.0 | 5.0 | — |
| Mettle | — | — | — | — | — | 5.0 | — | — | 5.0 | 5.0 | — | — |
| N26 | — | — | — | — | — | — | — | — | — | — | — | 3.0 |
| Qonto | — | — | — | — | — | — | — | 2.5 | — | — | — | — |
| Mercury | — | — | — | — | — | — | 4.0 | — | — | — | — | — |
| Cashplus | — | — | — | — | — | — | — | — | — | — | — | 5.0 |
| Chime | — | — | — | — | — | — | — | — | — | — | — | 5.0 |
| Zempler Bank | — | 5.0 | — | — | — | — | — | — | — | — | — | — |
| Airwallex | — | — | — | — | — | — | — | — | — | 5.0 | — | — |
| Bunq | — | — | — | — | — | — | — | — | — | — | — | 5.0 |
| Iwoca | — | — | — | — | — | — | — | — | — | — | — | 5.0 |
| Petal | — | — | — | — | — | — | — | — | — | — | — | 5.0 |
| Virgin Money | — | — | — | — | — | — | — | — | — | — | — | 5.0 |
A dash means that model never named the brand in any of its runs. Deeper blue is better: rank 1 is the brand a model would recommend first.
Where the models disagree
3 of 18 brands split the panel. Each mark is one model's score for the brand, on the same 0–100 scale as the ranking.
- #5Wise0100
mistral-medium-3.5 0 → claude-haiku-4.5 94 · 2 of 12 never named it
- #4Monzo0100
claude-haiku-4.5 0 → qwen3.8-max 80 · 1 of 12 never named it
- #1Starling Bank0100
claude-haiku-4.5 46 → qwen3.8-max 100
- from here down, the models agree
- #3Tide0100
gemini-3.5-flash-lite 40 → claude-opus-5 100
- #2Revolut0100
gemini-3.8-flash 52 → mistral-medium-3.5 100
- #6Anna Money0100
claude-haiku-4.5 0 → mistral-medium-3.5 20 · 6 of 12 never named it
A hollow mark is a model that never named the brand in any of its runs, which scores 0. Agreement is not endorsement — a brand every model ignores equally agrees just as tightly as one they all rank first.
Named, and named first
Across → how frequently the panel names the brand at all.
Up ↑ how often the answers that name it put it first.
- 1Starling Bank99/61
- 2Revolut100/20
- 3Tide99/13
- 4Monzo91/1
- 5Wise68/7
- 6Anna Money18/0
- 7Mettle8/0
- 8N263/0
The horizontal line sits at 20% — the rate a named brand would lead at if the models were picking one of its 5 slots at random. Above it they are choosing it first on purpose. Both figures average across models, so a thinly sampled model counts the same as a heavily sampled one.
What the models actually said
- Models
- 12
- Answers
- 114
Starling Bank leads with a score of 87 of 100, ranked by 12 of 12 models.
The twelve models show strong consensus on the top tier of UK neobanks for startups but diverge sharply on the criteria that should separate them. Starling Bank, Revolut, and Tide appear in every model's rankings, yet each model weights their strengths differently, producing a clear three-way split at the front of the field. Behind this leading group, opinions fracture along geographic and structural lines, with some brands appearing as category errors rather than genuine contenders.
Starling Bank · 54 points apart on a 0–100 scale
Starling achieves the highest brand score at 86.5, with seven models placing it first and two more at rank two. The enthusiastic cohort emphasizes FSCS-protected deposits, zero monthly fees, and integrations with Xero and QuickBooks, drawing heavily on Which?×31 and Trustpilot×82 to frame it as the safest, most complete primary banking option. The models ranking it lower do not dispute these qualities but argue that startups seeking rapid international scaling or venture-focused features would find Starling's core banking focus limiting. The split is less about Starling's actual capabilities and more about whether a model interprets "startup" to mean a regulated, steady-growth company or a high-velocity, multi-currency operation.
Revolut presents the inverse pattern. Two models rank it first in every run, yet the remaining ten settle it firmly at median rank three, producing a brand score of 69.17. The divide turns on multi-currency strength versus domestic friction. Models citing Siftedsifted.eu×30 and TechCrunch×22 praise its interbank FX rates, bulk payments, and API, framing it as essential for globally oriented teams. Those ranking it lower flag its e-money status, mobilisation-restricted UK banking licence, and compliance friction documented on Trustpilot×82. The hypothesis that emerges is that models trained or tuned on fintech industry sources weight international capability more heavily, while those drawing on retail banking comparisons prioritize deposit safety and customer-service stability.
- 98deepseek-v4.1-flash42
- 100gpt-6-astra46
- 100qwen3.8-max48
- 100gemini-3.7-flash55
- 100gemini-3.8-flash56
- 100grok-4.676
- 98gpt-5.6-luna76
- 80mistral-medium-3.560
- 90kimi-k380
- 48gemini-3.5-flash-lite40
- 46claude-haiku-4.544
- 78claude-opus-5100
Starling Bank ahead on 11 of 12 models
Tide illustrates a third axis of disagreement: startup-specific tooling versus scalability. One model ranks it first across all runs, four cluster it at rank two, and seven place it third or fourth, yielding a brand score of 60.25. The models praising Tide highlight rapid onboarding, invoicing, expense automation, and UK SME market share, citing its own site and Trustpilot×82. The skeptics acknowledge the same features but note that Tide operates as an e-money provider partnering with ClearBank rather than holding a full licence, and that its per-transaction fees accumulate as volume grows. This split plausibly reflects whether a model's reasoning weights administrative convenience for pre-revenue founders or financial infrastructure for post-seed growth.
Monzo exposes the broadest disagreement in the panel, with a brand score of 49.25 and per-model scores spanning zero to eighty. Four models place it at rank two, valuing its consumer-grade UX and tax-pot features for small founding teams; seven others assign rank four or five, noting thinner multi-currency support and features locked behind paid tiers. The sources are consistent across both camps—Which?×31, Trustpilot×82, The Guardian×12—but models interpret them to opposite ends. The hypothesis is that models emphasizing founder experience and simplicity elevate Monzo, while those focusing on operational depth and scale potential demote it.
Wise generates the sharpest single-model outlier. One model awards it a brand score of 94 and ranks it first, while ten others place it fifth with scores between four and twenty, and two omit it entirely. The lone advocate cites its multi-currency excellence and transparent FX as essential for globally operating startups, invoking Wise official websitewise.com×6 and Finder UK×2. The majority counter that Wise is an e-money institution lacking FSCS protection, overdrafts, and domestic payment rails, positioning it as a complementary payments layer rather than a primary bank. This is less a disagreement about Wise's capabilities and more about whether the question "neobank for a UK startup" permits a specialist international tool or demands an all-in-one domestic account.
Beyond the core five, the category collapses into brands that most models ignore entirely. Anna Money, Mettle, N26, Qonto, and Mercury each appear in six or fewer models' rankings, and those that do rank them place them last. The reasoning is categorical rather than evaluative: Anna and Mettle are seen as micro-business or freelancer tools that startups will outgrow; N26 and Qonto are European platforms with weak UK footprints; Mercury serves US-incorporated companies and is geographically ineligible for most UK Ltd structures. The handful of models naming these brands cite Startups.co.uk×12, NerdWallet×13, and provider sites, but the consensus is that they sit outside the neobank-for-UK-startup frame the question establishes.
The recalled sources cluster into three groups. Review aggregators—Trustpilot×82 cited eighty-two times, Which?×31 thirty-one times—appear across all models and all brands, serving as a common evidence base. Fintech industry outlets—Siftedsifted.eu×30, TechCrunch×22—tilt models toward international capability and venture-backed priorities. Provider sites and UK SME comparison sources like Tidewww.tide.co×29 and Starling Bankwww.starlingbank.com×19 ground assessments in stated features and regulated status. The hypothesis is that models weighting fintech press favor Revolut and Wise, while those weighting consumer-finance guides favor Starling and Monzo, and those balancing both land on Tide or split their top ranks between Starling and Revolut depending on the startup profile they imagine.
The deepest divide is not between individual brands but between two mental models of what a UK startup needs: a safe, regulated, full-service bank that integrates with UK accounting software and offers FSCS protection, or a multi-currency, API-rich platform optimized for cross-border payments and rapid scaling. Starling wins the former frame; Revolut wins the latter. Tide offers a middle path, startup-specific but domestically focused. Every other brand either duplicates one of these three propositions with less conviction or addresses a use case the question did not specify.
What shaped the answers
208 sources across 1477 references, grouped by site from 504 recalled names. The top 5 carry 40% of them.
Sources are what each model recalled as having shaped its view. It does not mean that the sources were actually used in training. Recalled URLs might also be invalid or hallucinated.
uk.trustpilot.com
- ×82named without a URL
- ×21/review/tide.co
- ×19/review/starlingbank.com
- ×18/review/monzo.com
- ×15/review/revolut.com
- ×14/
- ×14/review/wise.com
- ×4/review/www.revolut.com
- ×2/review/www.tide.co
- ×1/review/anna.money
Starling Bank
also named Starling, Starling Business
Summary
Starling Bank achieves a brand score of 86.5 and a first choice score of 76.63, reflecting very strong consensus that it is the core everyday banking option for UK startups. All twelve models ranked the brand, with per-model scores spanning 46–100. Seven models placed it first in every or nearly every run, while two positioned it consistently at rank two, and the remaining three spread it between ranks three and four. This distribution shows the panel broadly agrees Starling is a top-tier choice, though models diverge on whether it should lead outright or sit just behind more startup-specialized rivals.
per-model scores 46–100 of 100 · mean 87 across 12 models
The themes behind these rankings center on safety, cost, and functional completeness. Models repeatedly cite Starling's full UK banking licence with FSCS protection up to £85,000, zero monthly fees on standard business accounts, and seamless integrations with accounting platforms like Xero and QuickBooks. Sources invoked most often include Trustpilot×82, Which?×31, and Starling's own business-account pages, alongside mentions of CMA service-quality surveys and the FCA register. Where models rank it lower, they note that while Starling delivers reliable core banking, it lacks the startup-specific onboarding tools, multi-currency strength, or venture-focused features of competitors built expressly for high-growth companies. The split centers on whether a startup prioritizes regulated safety and proven service quality or wants features tailored to rapid international scaling and equity operations.
“Starling's full UK banking licence with FSCS protection, no monthly fees, strong accounting integrations, reliable app, and consistently high customer service ratings combine to make it the strongest, safest, and most complete everyday banking choice for UK startups.”
“Starling is positioned as the top recommendation for UK startups because it combines a full UK banking licence with FSCS protection, strong accounting integrations, and a complete business current account that serves as a reliable primary banking relationship rather than just a lightweight payment app.”
Per model summary
- deepseek-v4.1-flash
- brand score
- 98
- first choice
- 95
- median rank
- 1.0
- present in
- 10/10
Starling is positioned as the strongest all-round default for most UK startups, combining full UK banking licence, FSCS protection, no monthly fees, and solid accounting integrations in a reliable, practical package for day-to-day sterling banking.
- gemini-3.7-flash
- brand score
- 100
- first choice
- 100
- median rank
- 1.0
- present in
- 4/4
Starling's full UK banking licence, FSCS protection, zero monthly fees, seamless accounting integrations, and award-winning support combine to make it the premier secure, cost-effective, and reliable choice for early-stage UK startups.
- gemini-3.8-flash
- brand score
- 100
- first choice
- 100
- median rank
- 1.0
- present in
- 10/10
Starling's full UK banking licence with FSCS protection, zero monthly fees, award-winning interfaces, and seamless accounting integrations make it the most reliable, cost-effective, and scalable foundation for early-stage UK startups.
- gpt-5.6-luna
- brand score
- 98
- first choice
- 95
- median rank
- 1.0
- present in
- 10/10
Starling is recommended as a strong all-round default for UK startups wanting straightforward day-to-day banking, combining a well-regarded mobile experience, UK bank account with FSCS protection, useful integrations, and no monthly fee on its basic business account.
- gpt-6-astra
- brand score
- 100
- first choice
- 100
- median rank
- 1.0
- present in
- 10/10
Starling is positioned as the default first choice for typical UK startups trading mainly in pounds, offering a core business account with no monthly fee, useful accounting integrations, FSCS protection, and straightforward domestic banking, though international operations may require additional providers.
- grok-4.6
- brand score
- 100
- first choice
- 100
- median rank
- 1.0
- present in
- 10/10
Starling's full UK banking licence with FSCS protection, free business account, strong accounting integrations, reliable app, and consistently high customer service ratings combine to make it the strongest, safest, and most complete everyday banking choice for UK startups.
- qwen3.8-max
- brand score
- 100
- first choice
- 100
- median rank
- 1.0
- present in
- 10/10
Starling is positioned as the top recommendation for UK startups because it combines a full UK banking licence with FSCS protection, strong accounting integrations, and a complete business current account that serves as a reliable primary banking relationship rather than just a lightweight payment app.
- kimi-k3
- brand score
- 90
- first choice
- 75
- median rank
- 1.5
- present in
- 10/10
Starling's status as a fully licensed UK bank with FSCS protection, fee-free business account, excellent app, top customer satisfaction rankings, and award-winning service make it the safest and most dependable all-round primary account for UK startups, though slightly less startup-specific than some competitors.
- claude-opus-5
- brand score
- 78
- first choice
- 48
- median rank
- 2.0
- present in
- 10/10
Starling's full UK banking licence with FSCS protection up to £85,000, free business account, and top-rated service quality make it the safest and most reliable choice for UK startups, though it lacks the multi-currency and venture-specific features of more specialized competitors.
- mistral-medium-3.5
- brand score
- 80
- first choice
- 50
- median rank
- 2.0
- present in
- 10/10
Starling offers a fully FCA-regulated business account with no monthly fees, strong API access, and transparent pricing, making it a reliable and trustworthy option for UK startups prioritizing regulatory compliance and simplicity.
- gemini-3.5-flash-lite
- brand score
- 48
- first choice
- 29
- median rank
- 3.5
- present in
- 10/10
Starling delivers a fully regulated, FSCS-protected banking experience with zero monthly fees and excellent UK customer service, though its multi-currency and international capabilities lag behind specialized fintech competitors.
- claude-haiku-4.5
- brand score
- 46
- first choice
- 28
- median rank
- 4.0
- present in
- 9/10
Starling is consistently recognized as a solid, well-regulated UK bank with good core functionality, but is viewed as falling short on startup-specific features, international capabilities, and specialized tools compared to competitors focused on fast-growing businesses.
Sources per model
Each model’s own references for this brand, grouped by site. Tile area is that site’s share of the model’s references; tap one for the pages behind it.
starlingbank.com
- ×5/
- ×3Official website /business
- ×1Starling Bank Business Accounts /business-accounts
- ×1/business-banking
starlingbank.com
- ×12/business-account
- ×3CMA Service Quality Survey for business current accounts /service-quality-results
- ×1CMA Service Quality Survey for business current accounts /
starlingbank.com
- ×7/business-account
- ×2Starling Bank /business
- ×1Starling Bank business account pricing /business-account/pricing
- ×1Starling Bank Business /business-bank-account
- ×1Starling Business Account Banking Charges /legal/business-account-banking-charges
- ×1Starling Bank Marketplace /marketplace
Sources are what each model recalled as having shaped its view. It does not mean that the sources were actually used in training. Recalled URLs might also be invalid or hallucinated.
Revolut
also named Revolut Business
Summary
Revolut achieves a brand score of 69.17 and a first choice score of 48.47, with every model in the panel naming it. Two models—gemini-3.5-flash-lite and mistral-medium-3.5—rank it first in every run, drawn by its multi-currency accounts, competitive foreign-exchange rates, expense management, and API integrations for startups with international ambitions. The remaining ten models place it consistently at median rank 3, with per-model scores spanning 52 to 100. This broad agreement reflects a shared view: Revolut excels for cross-border operations but carries friction that keeps it from universal first place for a purely domestic UK startup.
per-model scores 52–100 of 100 · mean 69 across 12 models
The consensus narrative centres on three themes. First, models praise its international capabilities—multi-currency balances, interbank FX, bulk payments, and team cards—especially for startups paying overseas suppliers or hiring globally, cited through sources including Revolut Businesswww.revolut.com/business×37, TechCrunch×22, and Siftedsifted.eu×30. Second, regulatory and protection concerns recur: several models note that Revolut's UK business accounts historically operated under e-money permissions rather than full FSCS deposit insurance, and that its UK banking licence (granted in 2024) remains in mobilisation with restrictions, reducing confidence as a sole primary account. Third, customer support and compliance friction appears across Trustpilot×82, with models citing reports of account freezes during compliance reviews, chat-based support responsiveness, and tiered pricing that becomes expensive at scale. Models agree Revolut is strongest when international payments are central, but advise caution for startups whose operations are chiefly domestic and sterling-based.
“Revolut Business is strongest for startups with international operations, offering multi-currency accounts, interbank-rate FX, local IBANs in several regions, expense cards and a solid API.”
“Revolut Business excels for startups needing multi-currency accounts and international payments at competitive rates. However, it's not a fully licensed bank (e-money), so funds aren't FSCS-protected, and free plan limits may push startups to paid tiers quickly.”
Per model summary
- gemini-3.5-flash-lite
- brand score
- 100
- first choice
- 100
- median rank
- 1.0
- present in
- 10/10
Revolut Business is the top recommendation for UK startups due to its comprehensive multi-currency accounts, robust expense management tools, seamless integrations, and scalability for global operations. The platform is feature-rich and versatile, though customer support can occasionally be difficult to reach.
- mistral-medium-3.5
- brand score
- 100
- first choice
- 100
- median rank
- 1.0
- present in
- 10/10
Revolut is a top choice for UK startups due to its business accounts with multi-currency support, competitive FX rates, seamless integrations with accounting tools, and valuable API and expense management features. Its global reach makes it ideal for startups with international ambitions and scaling needs.
- claude-haiku-4.5
- brand score
- 82
- first choice
- 63
- median rank
- 2.0
- present in
- 10/10
Revolut offers comprehensive business features—multi-currency accounts, expense management, integrations, and competitive pricing—that suit internationally-focused startups. Regulatory scrutiny and customer service issues are recurring concerns that prevent it from ranking higher.
- gemini-3.7-flash
- brand score
- 70
- first choice
- 42
- median rank
- 2.5
- present in
- 4/4
Revolut Business excels for startups with international operations, offering competitive multi-currency accounts, low-cost FX, and advanced treasury tools. The lack of full UK FSCS deposit protection and historical issues with compliance-related account freezes and customer support response times are recurring drawbacks.
- claude-opus-5
- brand score
- 62
- first choice
- 35
- median rank
- 3.0
- present in
- 10/10
Revolut Business is strongest for startups with international operations, offering multi-currency accounts, interbank-rate FX, and a solid API. Its UK banking licence (in mobilisation) improves credibility, but patchy support and occasional account freezes during compliance reviews remain significant drawbacks.
- deepseek-v4.1-flash
- brand score
- 64
- first choice
- 37
- median rank
- 3.0
- present in
- 10/10
Revolut Business excels for startups needing multi-currency accounts and international payments at competitive rates. Its UK business accounts lack FSCS protection (operating as e-money rather than a full bank), making it better suited as a secondary account, and customer support quality is inconsistent.
- gemini-3.8-flash
- brand score
- 52
- first choice
- 30
- median rank
- 3.0
- present in
- 10/10
Revolut Business is the strongest platform for tech startups operating internationally, offering competitive FX, multi-currency accounts, and powerful APIs. Its complex tiered pricing, historical e-money status rather than full UK banking licence, and inconsistent customer support during compliance reviews are consistent concerns.
- gpt-5.6-luna
- brand score
- 64
- first choice
- 37
- median rank
- 3.0
- present in
- 10/10
Revolut is a strong choice for startups with international customers, contractors, or multi-currency needs, offering competitive foreign-exchange functionality and expense tools. Its feature set and tiered pricing can be more complex than traditional UK business banks, making it best suited as a complementary rather than sole banking relationship.
- gpt-6-astra
- brand score
- 54
- first choice
- 31
- median rank
- 3.0
- present in
- 10/10
Revolut is particularly attractive for startups paying overseas suppliers or managing multiple currencies, with strong international payments and team-spending tools. For mainly domestic startups, plan fees, usage allowances, and the need to verify the legal entity and deposit protection applicable to the account warrant closer scrutiny.
- grok-4.6
- brand score
- 64
- first choice
- 37
- median rank
- 3.0
- present in
- 10/10
Revolut Business excels for internationally minded startups with multi-currency accounts, competitive FX, and team expense controls in a feature-rich platform. Its UK e-money status (lacking full FSCS protection), occasional support and compliance friction, and scaling fees keep it from ranking higher as a primary domestic account.
- kimi-k3
- brand score
- 66
- first choice
- 42
- median rank
- 3.0
- present in
- 10/10
Revolut Business is excellent for startups with international operations, offering multi-currency accounts, competitive FX, and strong spend controls. Its recently granted UK banking licence (still in mobilisation with restrictions), recurring reports of account freezes, and historically variable support make it less reassuring as a primary UK banking home.
- qwen3.8-max
- brand score
- 52
- first choice
- 30
- median rank
- 3.0
- present in
- 10/10
Revolut Business is attractive for startups with international payments, multi-currency needs, or global contractors, offering strong FX and spend controls. It ranks lower as a main UK business account because its core UK banking proposition feels less straightforward than traditional bank-licensed alternatives for primarily domestic operations.
Sources per model
Each model’s own references for this brand, grouped by site. Tile area is that site’s share of the model’s references; tap one for the pages behind it.
trustpilot.com
revolut.com
- ×6/business
- ×4Revolut Business Pricing /business/business-account-plans
- ×2/en-GB/business
- ×1/business/business-account
- ×1/en-GB/business/business-account
- ×1Revolut Business pricing /en-GB/business/business-account-plans
- ×1Revolut Business Pricing /en-GB/business/pricing
revolut.com
- ×1/business
- ×1/
- ×1Revolut Business /business
- ×1Revolut Business /en-GB/business
- ×1named without a URL
Sources are what each model recalled as having shaped its view. It does not mean that the sources were actually used in training. Recalled URLs might also be invalid or hallucinated.
Tide
Summary
Tide achieves solid consensus across the panel as a strong neobank for UK startups, recording a brand score of 60.25 and appearing in every model's rankings. The 12 models deliver scores spanning 40 to 100, which the study labels "broad agreement," yet the practical distribution is revealing: one model ranks it first on every run, several cluster it at rank two, and the remainder place it third or fourth. This split reflects a consistent pattern in the underlying reasoning—models uniformly praise Tide's startup-tailored features like rapid onboarding, integrated invoicing, expense management, and accounting software connections, yet they diverge sharply on whether its e-money institutional structure and accumulated transaction fees should hold it back from the top position.
per-model scores 40–100 of 100 · mean 60 across 12 models
The divide turns on two core themes. Models that rank Tide first or second emphasise that its administrative tooling maps directly onto early-stage needs, citing Tidewww.tide.co×29 and Trustpilot×82 to underline market share among UK SMEs and fast, often same-day account opening. Those placing it third or fourth acknowledge the same strengths but weigh more heavily the fact that Tide operates as an e-money provider partnering with ClearBank rather than holding its own full banking licence, a distinction they flag as relevant for deposit protection and long-term scalability. The models also split on fee sensitivity: some view the free tier as ideal for pre-revenue companies, while others warn that per-transaction charges can accumulate as volume grows, making Tide less attractive than flat-fee competitors once a startup scales.
“Tide is purpose-built for UK small businesses with the largest digital challenger market share, offering fast onboarding, free company incorporation, and strong accounting integrations, though its main limitation is being an e-money/agency banking model rather than a full bank.”
“Tide is highly focused on small businesses with fast onboarding and useful administration features like invoicing and bookkeeping in one place, though founders should carefully check pricing, fee schedules, account structure, and protection arrangements because it is a fintech platform rather than a traditional bank.”
Per model summary
- claude-opus-5
- brand score
- 100
- first choice
- 100
- median rank
- 1.0
- present in
- 10/10
Tide is purpose-built for UK small businesses with the largest digital challenger market share, offering fast onboarding, free company incorporation, and strong accounting integrations, though its main limitation is being an e-money/agency banking model rather than a full bank.
- gpt-5.6-luna
- brand score
- 76
- first choice
- 51
- median rank
- 2.0
- present in
- 10/10
Tide is highly focused on small businesses with fast onboarding and useful administration features like invoicing and bookkeeping in one place, though founders should carefully check pricing, fee schedules, account structure, and protection arrangements because it is a fintech platform rather than a traditional bank.
- grok-4.6
- brand score
- 76
- first choice
- 47
- median rank
- 2.0
- present in
- 10/10
Tide is purpose-built for UK small businesses bundling a current account with invoicing, expense tracking, and bookkeeping tools that suit early-stage companies, though it is an e-money institution rather than a fully licensed bank, meaning deposits are safeguarded rather than FSCS-protected.
- kimi-k3
- brand score
- 80
- first choice
- 65
- median rank
- 2.0
- present in
- 10/10
Tide is purpose-built for UK small businesses and startups with very fast onboarding, integrated invoicing, expense management, and accounting integrations that map almost exactly to early-stage needs, though it operates as an e-money institution through partner banks rather than holding its own full banking license.
- claude-haiku-4.5
- brand score
- 44
- first choice
- 26
- median rank
- 3.0
- present in
- 9/10
Tide is purpose-built for UK small businesses with accounting integrations and invoicing, but its more limited international capabilities, narrower feature set, and less polished platform compared to competitors place it in the middle tier for ambitious growth-stage startups.
- gemini-3.8-flash
- brand score
- 56
- first choice
- 33
- median rank
- 3.0
- present in
- 10/10
Tide is explicitly designed for small UK businesses with exceptionally fast onboarding and powerful administrative tools like invoicing and expense categorization, but it operates as an e-money provider via partner banks rather than holding its own full banking license, and per-transaction fees can accumulate as volume grows.
- mistral-medium-3.5
- brand score
- 60
- first choice
- 33
- median rank
- 3.0
- present in
- 10/10
Tide is tailored specifically for small businesses and startups with quick account setup, invoicing tools, and accounting integrations, though it lacks some advanced features like robust multi-currency accounts and may be less scalable compared to competitors.
- gemini-3.7-flash
- brand score
- 55
- first choice
- 33
- median rank
- 3.5
- present in
- 4/4
Tide is engineered specifically for UK small businesses with rapid setup, integrated invoicing, and automated bookkeeping, but it operates as an e-money institution via partner banking rather than a full bank license, and transaction fees can accumulate quickly for higher-volume businesses.
- deepseek-v4.1-flash
- brand score
- 42
- first choice
- 27
- median rank
- 4.0
- present in
- 10/10
Tide is quick to open with low costs and useful features for early-stage companies, but it is not a full bank and lacks FSCS protection, making it less suitable as a startup's primary account despite its popularity and safeguarded funds via partner banks.
- gemini-3.5-flash-lite
- brand score
- 40
- first choice
- 26
- median rank
- 4.0
- present in
- 10/10
Tide offers very quick digital onboarding, built-in invoicing, and automated expense tools tailored for UK small businesses, but users report account freezes during compliance checks, transaction fees that accumulate at scale, and limitations for companies with complex international or treasury needs.
- gpt-6-astra
- brand score
- 46
- first choice
- 28
- median rank
- 4.0
- present in
- 10/10
Tide is appealing for combining business banking with invoicing, bookkeeping, and company administration tools, but transaction charges and paid extras can affect its value, and because Tide is a financial platform rather than a bank itself, the underlying account provider and protection arrangements must be checked.
- qwen3.8-max
- brand score
- 48
- first choice
- 28
- median rank
- 4.0
- present in
- 10/10
Tide is practical for fast setup with useful invoicing, expense tools, and accounting connections for early-stage companies, but it feels more like a business finance platform than a full-service bank, which may limit its suitability as a primary long-term banking relationship as the startup scales.
Sources per model
Each model’s own references for this brand, grouped by site. Tile area is that site’s share of the model’s references; tap one for the pages behind it.
tide.co
- ×4/pricing
- ×3Tide /business-account
- ×2Tide Business Bank Accounts /business-bank-account
- ×2Tide business banking /business-banking
- ×1Tide /
- ×1Tide /business-current-account
- ×1Tide Companies House Formation /company-formation
- ×1Tide /features/business-bank-account
Sources are what each model recalled as having shaped its view. It does not mean that the sources were actually used in training. Recalled URLs might also be invalid or hallucinated.
Monzo
also named Monzo Business
Summary
Monzo achieves a brand score of 49.25 across the panel, with eleven of twelve models naming it but opinions sharply divided: per-model scores range from 0 to 80, earning the "models split" designation. The core tension is between Monzo's widely praised consumer-grade app experience and a business feature set that many models regard as less mature than specialist rivals. Models consistently applaud its intuitive interface, instant notifications, and tax-pot automation, citing sources such as Trustpilot×82, G2×22, and Which?×31. Yet most position it behind Starling or Tide for startups expecting to scale, pointing to thinner multi-currency support, fewer accounting integrations on free tiers, and a product legacy rooted in personal rather than business banking.
per-model scores 0–80 of 100 · mean 49 across 12 models
The disagreement shows clearly in rank: four models place Monzo at rank two, valuing simplicity and UX polish for small founding teams, while seven others assign rank four or five, emphasizing its limited appeal for international operations, complex finance workflows, and larger teams. Multiple models note that advanced business capabilities—invoicing, multi-user access, deeper integrations—sit behind paid subscriptions, diluting its cost advantage. The split reflects whether a given model weights founder-friendliness and FSCS-protected ease of use above breadth of tooling; those prioritizing the former score Monzo near the top, while those focusing on startup scale and operational depth rank it mid-pack or lower.
“Monzo Business is praised for its user-friendly app, FSCS protection, and helpful features like tax pots and accounting integrations, but it is recognized as less feature-rich than rivals for complex international needs or larger teams.”
“Monzo's business accounts are user-friendly and excel in transparency and ease of use, making them great for sole traders and micro-startups, but they lack advanced features like multi-currency support that more complex or scaling businesses require.”
Per model summary
- deepseek-v4.1-flash
- brand score
- 74
- first choice
- 49
- median rank
- 2.0
- present in
- 10/10
Monzo Business is praised for its user-friendly app, FSCS protection, and helpful features like tax pots and accounting integrations, but it is recognized as less feature-rich than rivals for complex international needs or larger teams.
- gemini-3.8-flash
- brand score
- 72
- first choice
- 45
- median rank
- 2.0
- present in
- 10/10
Monzo provides full UK bank licensing, FSCS protection, and an exceptionally intuitive mobile-first experience with automated tax pots, but its best startup functionality and advanced features require paid tiers rather than being available on the free plan.
- gpt-6-astra
- brand score
- 80
- first choice
- 50
- median rank
- 2.0
- present in
- 10/10
Monzo is a strong choice for founders who value an intuitive app, spending visibility, and simple day-to-day administration with FSCS protection, but some of its most useful business features require paid plans, placing it slightly behind Starling for cost-conscious startups.
- qwen3.8-max
- brand score
- 80
- first choice
- 50
- median rank
- 2.0
- present in
- 10/10
Monzo Business is praised for its very intuitive app, simple expense management features, and ease of use for small founding teams, but it is seen as slightly less comprehensive and mature than Starling for complex finance operations and scaling startup needs.
- gemini-3.7-flash
- brand score
- 55
- first choice
- 33
- median rank
- 3.5
- present in
- 4/4
Monzo offers full UK licensing, FSCS protection, and an intuitive mobile experience with useful features like tax pots and invoicing, but many advanced capabilities require paid subscription tiers, making it less cost-effective for larger teams.
- claude-opus-5
- brand score
- 34
- first choice
- 24
- median rank
- 4.0
- present in
- 10/10
Monzo is a fully licensed UK bank with FSCS protection and an excellent app, but its business feature set is narrower than competitors—particularly for multi-currency, international payments, and scaling startups—making it better suited to UK-only, domestic operations and simpler company structures.
- gemini-3.5-flash-lite
- brand score
- 38
- first choice
- 26
- median rank
- 4.0
- present in
- 9/10
Monzo brings its acclaimed consumer app experience to business banking with intuitive interface and tax pots, but its offering is geared more toward freelancers and micro-businesses than scaling startups, with a feature set that remains basic compared to dedicated business neobanks.
- gpt-5.6-luna
- brand score
- 42
- first choice
- 26
- median rank
- 4.0
- present in
- 10/10
Monzo offers a polished, intuitive app and accessible business banking experience that works well for simple UK operations, but its business offering is less comprehensive than competitors for international operations, specialist startup tools, and complex finance workflows.
- grok-4.6
- brand score
- 40
- first choice
- 25
- median rank
- 4.0
- present in
- 10/10
Monzo Business inherits the polished consumer app experience with clean design and instant notifications that many founders already know, but its business-specific tools and feature depth remain less mature and specialized than dedicated SME neobanks.
- kimi-k3
- brand score
- 36
- first choice
- 24
- median rank
- 4.0
- present in
- 10/10
Monzo Business offers a polished app, FSCS protection, and handy features like tax pots that suit solo founders and very small teams, but its business feature set is thinner and less mature than rivals, limiting its appeal as startups scale.
- mistral-medium-3.5
- brand score
- 40
- first choice
- 25
- median rank
- 4.0
- present in
- 10/10
Monzo's business accounts are user-friendly and excel in transparency and ease of use, making them great for sole traders and micro-startups, but they lack advanced features like multi-currency support that more complex or scaling businesses require.
Sources per model
Each model’s own references for this brand, grouped by site. Tile area is that site’s share of the model’s references; tap one for the pages behind it.
monzo.com
- ×5/business
- ×5Monzo Business Banking /business-banking
- ×3Monzo Business Pricing /business-banking/pricing
- ×2Monzo /about
- ×2Monzo business account help /help/business
- ×1Monzo fees and plans /business-banking/business-account-fees
- ×1Monzo Business Pricing /business/pricing
Sources are what each model recalled as having shaped its view. It does not mean that the sources were actually used in training. Recalled URLs might also be invalid or hallucinated.
Wise
also named Wise Business
Summary
Wise draws sharply divided assessments from the models, with a brand score of 24.33 reflecting disagreement rather than consensus. One model consistently ranked it first across nearly all runs, awarding it a median rank of 1 and a per-model brand score of 94, while ten other models placed it at the bottom of their lists with a median rank of 5 and individual scores between 4 and 20. Two models omitted it entirely. This split produces a standard deviation of 25.71, labeled "models split" in the study's methodology.
per-model scores 0–94 of 100 · mean 24 across 12 models
The central theme uniting both enthusiastic and reserved recommendations is Wise's excellence in international payments and multi-currency operations. Models citing Wise official websitewise.com×6, Trustpilot×82, and Finder UK×2 consistently praised its mid-market exchange rates, transparent fee structure, and ability to hold balances in dozens of currencies with local account details. The divergence turns on a structural constraint: Wise is an electronic money institution rather than a full UK bank, meaning it lacks FSCS deposit protection, overdraft facilities, lending products, and some domestic payment rails. Models that ranked it highly emphasized its value for startups with cross-border operations, while those placing it fifth stressed that it works best as a complementary tool alongside a primary UK business bank rather than as a sole account. The first-choice score of 21.14 reflects that only one model positioned Wise as a lead recommendation; the remainder framed it as a specialist payments layer rather than an all-in-one neobank.
“Wise excels at international payments and multi-currency accounts, which are essential for UK startups operating globally. Their transparent pricing, strong regulatory compliance, and dedicated business accounts make them ideal for early-stage companies managing cross-border transactions.”
“Wise Business is excellent as a supplementary account for cross-border payments and paying overseas contractors at near mid-market FX rates, with local account details in 20+ currencies. However, it is not a bank, pays no meaningful protection under FSCS, and lacks Direct Debit collection, overdrafts and credit — so it works poorly as a startup's sole primary account.”
Per model summary
- claude-haiku-4.5
- brand score
- 94
- first choice
- 85
- median rank
- 1.0
- present in
- 10/10
Wise is consistently highlighted for its excellence in multi-currency transactions and international payments with transparent, competitive pricing, making it particularly valuable for UK startups with cross-border operations, though it has more limited business banking features compared to full-service neobanks.
- gemini-3.5-flash-lite
- brand score
- 60
- first choice
- 39
- median rank
- 2.0
- present in
- 9/10
Wise Business is exceptional for startups with cross-border transactions due to its unbeatable mid-market exchange rates and transparent, low-cost international transfers, though it lacks some traditional domestic banking features like lending or overdrafts and works best as a secondary account for international operations.
- claude-opus-5
- brand score
- 18
- first choice
- 17
- median rank
- 5.0
- present in
- 8/10
Wise Business is excellent for cross-border payments and multi-currency operations but is an e-money institution rather than a bank, lacking credit, overdrafts, FSCS protection, and full UK banking features, which makes it best used as a supplementary account alongside a primary UK business bank rather than as a sole account.
- deepseek-v4.1-flash
- brand score
- 20
- first choice
- 19
- median rank
- 5.0
- present in
- 9/10
Wise Business excels at international transfers and multi-currency holding with transparent fees, but because it is not a full UK bank and lacks FSCS protection, overdrafts, and lending, it works best as a secondary or companion account rather than a primary startup bank.
- gemini-3.7-flash
- brand score
- 20
- first choice
- 20
- median rank
- 5.0
- present in
- 4/4
Wise provides unrivaled mid-market exchange rates and multi-currency capabilities ideal for globally operating startups, but as an electronic money institution rather than a full UK bank, it lacks credit facilities, FSCS protection, and traditional domestic banking features, making it best suited as a complementary service alongside a primary UK business bank.
- gemini-3.8-flash
- brand score
- 20
- first choice
- 20
- median rank
- 5.0
- present in
- 10/10
Wise Business is unmatched for cost-effective international payments, mid-market exchange rates, and multi-currency account management, but because it operates as an electronic money institution rather than a full-service UK bank, it lacks lending products, FSCS protection, and comprehensive banking capabilities, making it best used as a complementary international account rather than a primary operational hub.
- gpt-5.6-luna
- brand score
- 4
- first choice
- 4
- median rank
- 5.0
- present in
- 2/10
Wise Business is excellent for transparent international payments and multi-currency balances, making it a valuable secondary account for globally oriented startups, but it is more of a payments and currency platform than a complete UK business banking solution.
- gpt-6-astra
- brand score
- 16
- first choice
- 16
- median rank
- 5.0
- present in
- 8/10
Wise is excellent for international transfers, receiving overseas revenue, and multi-currency functionality with transparent pricing, but it ranks fifth as a primary account because it is a payments provider rather than a bank, with safeguarded balances instead of FSCS-protected deposits, making it better suited as a companion to a full-service UK business bank.
- grok-4.6
- brand score
- 18
- first choice
- 18
- median rank
- 5.0
- present in
- 9/10
Wise Business excels at low-cost international transfers and multi-currency holding at real exchange rates, making it valuable for startups with overseas operations, but because it is not a full-service UK current account and lacks features like overdrafts and loans, it is best used as a specialist FX tool or complement rather than a primary neobank.
- kimi-k3
- brand score
- 22
- first choice
- 17
- median rank
- 5.0
- present in
- 7/10
Wise Business is outstanding for low-cost international payments and multi-currency operations, but because it is an e-money institution rather than a bank, it lacks FSCS protection, lending products, and full UK current-account features, making it best used as a complement to rather than a replacement for a primary startup bank.
Sources per model
Each model’s own references for this brand, grouped by site. Tile area is that site’s share of the model’s references; tap one for the pages behind it.
wise.com
- ×8/gb/business
- ×1Wise safeguarding /help/articles/2949821/how-wise-keeps-your-money-safe
wise.com
- ×8/gb/business
- ×1Wise safeguarding and licensing disclosures /gb/legal
- ×1Wise pricing and safeguarding disclosures /gb/pricing
- ×1Wise safeguarding / FSCS explainer /help
wise.com
- ×2/gb/business
- ×1Wise Customer Agreement /gb/legal/terms-of-use
- ×1Wise Help Centre /help
Sources are what each model recalled as having shaped its view. It does not mean that the sources were actually used in training. Recalled URLs might also be invalid or hallucinated.
How this was measured
The question
- Unaided brand recommendation question: “What neobank would you recommend for a UK startup?”
- The prompt asks each model to return exactly 5 brands, ranked 1 to 5, and for each one a reason for the recommendation and the sources that informed it.
Sampling
- Models are not deterministic, so the question is asked over and over — 10 answers per model
- Spellings of the same brand are normalized to the most commonly used form before counting
Measures of Position: Median and Quartiles
- Median value indicates that in 50% of answers the brand held this position or higher.
- Quartiles help visualize the spread of rankings per brand. Q1 indicates that 25% of answers had this rank or higher. Q3 means that 75% of answers ranked the brand as X or better.
- Medians and quartiles are computed only from answers where the brand was present.
Coverage
- Count of answers in which the given brand was named, as a percentage.
Brand score - Normalized Borda score
- The brand score is calculated using a normalized Borda score. Borda count is a voting method: each ballot awards points by position instead of naming one winner. Our ranking responses from the LLM are always fixed to 5 answers, so we assign 100 points for rank 1, then 80, 60, 40, 20 — and 0 if the brand is missing.
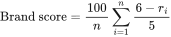
where
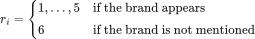
- This way we can calculate a common score for all brands mentioned across model responses. The score reflects both how high the brand was ranked and how frequently it was mentioned.
First choice score - adjusted MRR - top-rank indicator
- The first choice score is based on Mean Reciprocal Rank (a common search-engine measure), but adapted to measure the position of a specific brand across repeated ranked responses.
- Each occurrence receives a reciprocal-position score: 100 for 1st, 50 for 2nd, 33.3 for 3rd, 25 for 4th, 20 for 5th, and 0 when the brand is not mentioned. The scores are averaged across all responses.
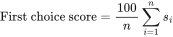
where
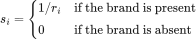
- No rank below 1st place gets more than 50, so the score is heavily driven by first places.
Browse other categories
Each one is a single question put to every active AI model, many times over.
Or scroll for more
- No Code Platforms#1 AirtableNo Code PlatformsWhat are the best no-code platforms for a company to build internal workflows and apps without developers?#1Airtable81#2Microsoft54#3Zapier3328 ranked
- AI Brand Visibility Tools#1 ProfoundAI Brand Visibility ToolsWhat AI brand visibility tool would you recommend?#1Profound73#2Peec AI48#3Semrush4031 ranked
- Airtable agencies#1 GAP ConsultingAirtable agenciesWhich Airtable agency would you recommend?#1GAP Consulting43#2Openside33#3On2Air31153 ranked
- Review response Hospitality#1 TrustYouReview response HospitalityWhat review response platform would you recommend for a hotel?#1TrustYou81#2Revinate67#3ReviewPro6223 ranked
- Form builders for small business#1 JotformForm builders for small businessWhich form builder would you recommend for a small business?#1Jotform97#2Typeform66#3Google Forms5416 ranked
- Running shoes for marathon#1 NikeRunning shoes for marathonWhat brand of running shoes would you recommend for a marathon?#1Nike85#2ASICS80#3Adidas488 ranked
- Downwind Foiling Boards#1 ArmstrongDownwind Foiling BoardsWhat brand would you recommend for an intermediate rider looking for a down winding board?#1Armstrong44#2Starboard37#3Sunova2535 ranked
- CRM Software#1 HubSpotCRM SoftwareWhat CRM software would you recommend?#1HubSpot95#2Salesforce85#3Zoho539 ranked
- Consulting companies for AI transformation#1 McKinsey & CompanyConsulting companies for AI transformationWhich consulting firm should a Fortune 500 company hire for an AI transformation?#1McKinsey & Company87#2Accenture78#3Boston Consulting Group638 ranked
- MBA Programs ROI#1 Stanford Graduate School of BusinessMBA Programs ROIWhich MBA program gives you the best return on investment?#1Stanford Graduate School of Business66#2Wharton46#3Harvard Business School4439 ranked
- AI models for coding#1 AnthropicAI models for codingWhich AI model would you recommend for coding?#1Anthropic90#2OpenAI74#3Google5215 ranked
- Business Podcasts#1 How I Built ThisBusiness PodcastsWhich business podcast would you recommend?#1How I Built This77#2Acquired54#3Masters of Scale4131 ranked
- Business Class airlines#1 Qatar AirwaysBusiness Class airlinesWhich airline would you recommend for business-class travel?#1Qatar Airways87#2Singapore Airlines84#3Emirates4216 ranked
- EV vehicles#1 TeslaEV vehiclesWhich EV brand would you recommend?#1Tesla90#2Hyundai76#3Kia3714 ranked
- Watch brands#1 OmegaWatch brandsWhich watch brand would you wear on a first date?#1Omega73#2Cartier62#3Seiko4331 ranked
Ask your own question of every model
Tell us what to ask and how wide to sample it — we run it and send back the report.